
Inactive· since Jul 6, 2026
- 8
- days it ran
- 1
- relaunches
Ad copy
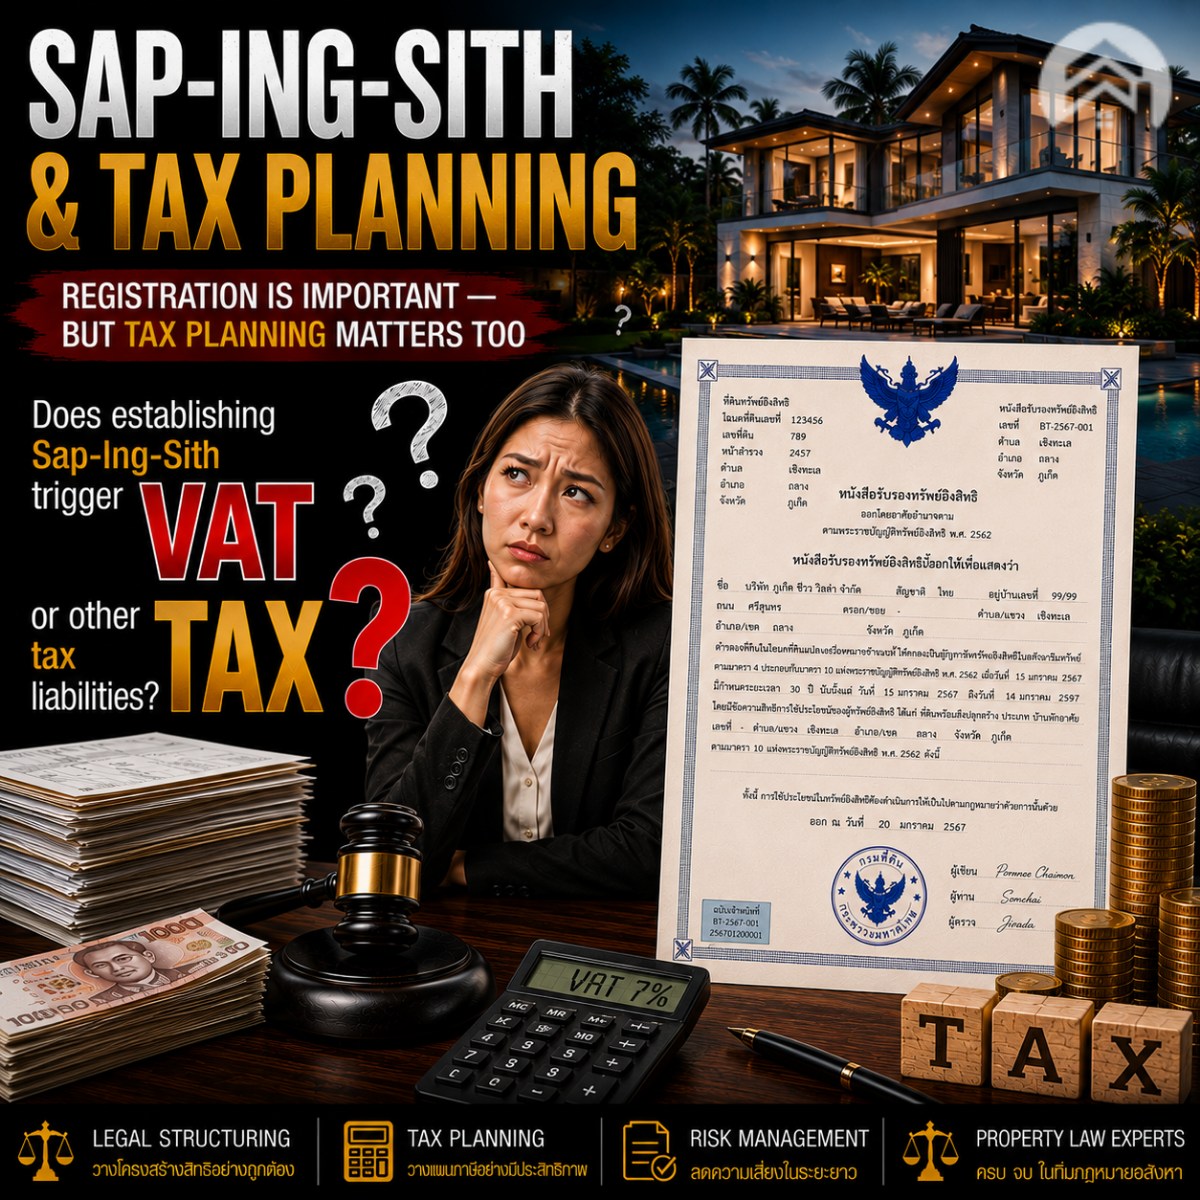
## 🏡 SAP-ING-SITH & TAX PLANNING‼️ ## 📌 Registration Is Important — But Tax Planning Matters Too . One of the most common questions we receive from investors is simple: . ❓ Does establishing Sap-Ing-Sith trigger VAT or other tax liabilities? . Recently, during Our “Property Investment & Legal Seminars”, several participants — including developers and property owners — raised exactly this question. . Some asked: . 💬 “Does establishing Sap-Ing-Sith require VAT?” 💬 “Why do we still have tax exposure after registration at the Land Office?” 💬 “Do you have ANY solutions for us to not pay TAX⁉️” 😱 . We intentionally did not answer this question in full during the seminar because the issue is more complex & sensitive than many investors assume. . ⚖️The Key Point is : The VAT treatment of Sap-Ing-Sith often depends on how the legal and commercial structure is designed from the beginning. . . 🔍 # Key Consideration: Nature of Income # . In practical terms, one key issue is how the Revenue Department may interpret the income arising from the transaction. . Is the income derived from: . 🏠 Rental income? or 🔄 Sale / transfer of rights arising from Sap-Ing-Sith? . 👉 This distinction can significantly affect tax treatment. . ✅ Rental income derived from immovable property may qualify for VAT exemption under Section 81(1)(t) of the Thai Revenue Code. . ⚠️ However, if the transaction is interpreted differently — particularly as income arising from the sale or transfer of rights — VAT implications may arise depending on the structure and facts of each case. . . ⚖️ # Additional Consideration: Usufruct & Superficies # . Similar issues also arise in relation to Usufruct (สิทธิเก็บกิน) and Superficies (สิทธิเหนือพื้นดิน) . In theory: . ✅ If such rights are registered with consideration (ค่าตอบแทน) and ✅ The property owner is a juristic person (company) . 👉 The transaction may fall within the scope of VAT. . However: . ✅ If the registration is made without consideration, and ✅ The parties are individuals (natural persons) . 👉 VAT may not apply. . In practice, this type of arrangement is commonly seen within family relationships, where rights are granted without commercial intent — and therefore VAT is typically not an issue. . ⚠️ # Practical Reality & Structuring Risks ‼️# . In recent years, some legal structures have attempted to rely on this distinction. Certain law firms have used these concepts — particularly usufruct or superficies — as part of structures designed for foreign clients. . 👉 Whether VAT applies, or whether it may be assessed later, depends heavily on: . • The wording of the contract • Whether consideration is clearly stated or implied • The relationship between the parties • The overall commercial substance of the arrangement . ⚠️ In some cases, even if VAT is not triggered at the time of registration, the Revenue Department may later recharacterize the transaction based on its economic reality. . . ⚠️ # Common Misunderstanding # . This is why we always caution investors against making assumptions based solely on registration outcomes. Many investors mistakenly believe that once fees and taxes are paid at the Land Office, everything is fully settled. . ❌ That is not always the case. . 🏢 The Land Office may collect registration fees and certain taxes, but this does not necessarily mean all future tax obligations have been fully assessed or finalized. . . 🎯 # The Real Question # . The real question is often not whether tax applies. . The real question is: 👉 What tax applies, to whom, and under which structure? . Depending on the structure, relevant tax considerations may include: . • 🏡 Land and Building Tax • 👤 Personal Income Tax • 🏢 Corporate Income Tax • 💰 Value Added Tax (VAT) . . 🧠 # Structure Planning Matters # . At House & Condo Lawyer, we always advise clients — especially foreign investors — to focus on proper legal structuring and lawful tax planning from the beginning. . ✅ The objective is not tax avoidance. ✅ The objective is to structure properly, allocate risks clearly, and ensure long-term compliance. . 🤖 With increasingly sophisticated AI-driven tax enforcement and cross-agency data verification between the Revenue Department, Land Department, and Ministry of Commerce: . ⚠️ Improper tax planning, aggressive tax avoidance, or undocumented arrangements are becoming far more difficult to sustain. . . 🚩WANT TO KNOW MORE: https://housecondolawyer.com/sap-ing-sith-right-over-lease-hold . . 🏆 WHY HOUSE & CONDO LAWYER? . Thailand Property Lawyers Focused Exclusively On 🏡 Real Estate, Ownership Structures & Property Protection . 🏆 15+ Years Real Estate Experience 🏆 1,000+ Property Cases Handled 🏆 300+ Cases Annually 🏆 100+ SAP-ING-SITH Structures Established Nationwide . We do far more than simply register Sap-Ing-Sith. We help clients structure: . ✔ Ownership Rights ✔ Contract Terms ✔ Tax Planning ✔ Risk Allocation . 📞 FIRST CONSULTATION FREE OF CHARGE Thinking about establishing Sap-Ing-Sith in Thailand? . 💡 Consult with us before making decisions. 👉 The difference is often not in the registration itself — but in the legal and tax strategy behind the structure. . 📩 Send us a message to discuss your case. . Facebook: House & Condo Lawyer International FB Inbox: http://m.me/housecondolawyerinter LINE: https://lin.ee/dDmufaL WhatsApp: http://wa.me/+66846236146 (English Speaking) Email: [email protected] www.housecondolawyer.com . ━━━━━━━━━━━━━━━━━━ . #RightoverLeaseHoldAsset #SapIngSith #BlueGarudaDeed #HouseAndCondoLawyer #ThailandPropertyLawyer #PropertyProtection #ForeignInvestmentThailand
Like this ad? Make it yours.
Crush rebuilds this exact creative around your product — your brand, your colors, your offer — in about a minute.