DMD Insurance Services
 Facebook ad: “Tired of Your Restaurants Premiums Going Up?”
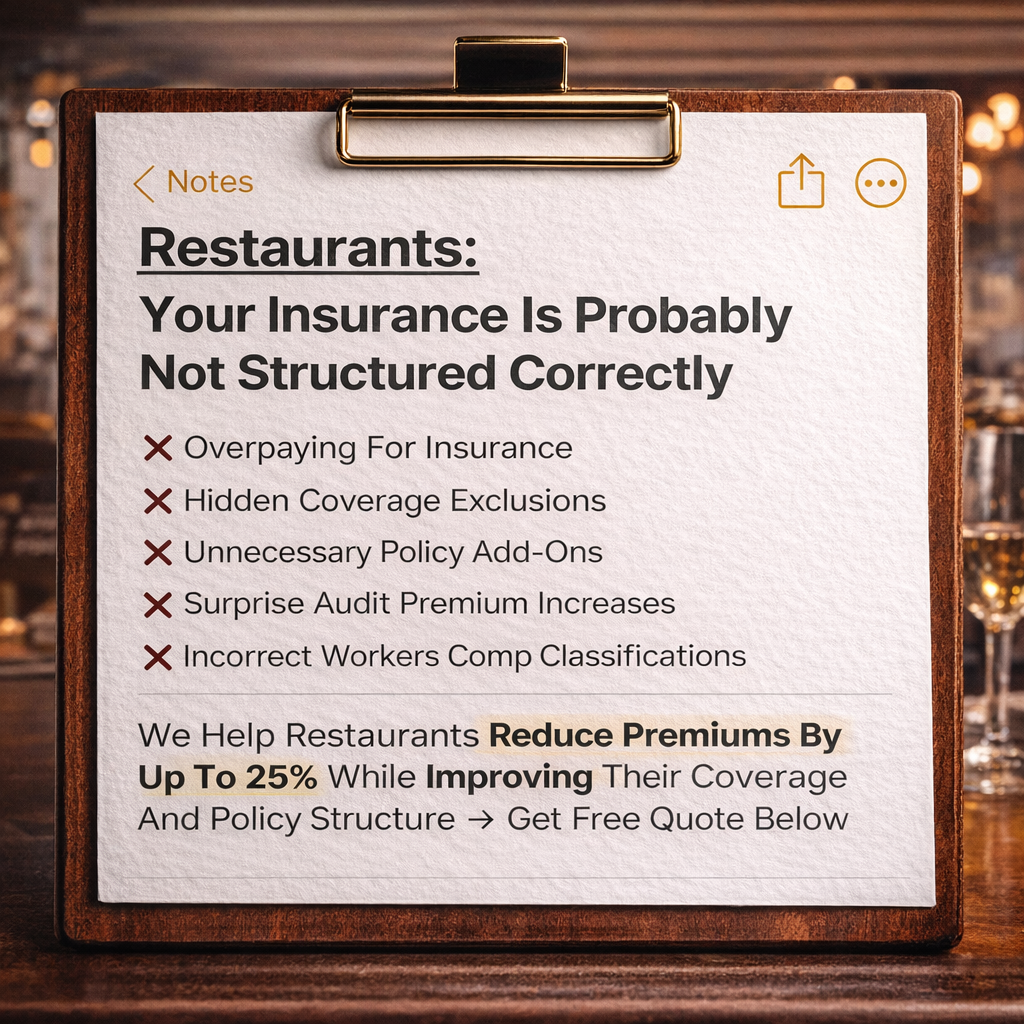
Ran for 2 days, from March 9 to March 11, 2026, the last day Crush saw it.
Run by DMD Insurance Services on Facebook. Crush is not the advertiser and does not verify its claims. See this ad in Meta's Ad Library(opens in a new tab)
Want an ad like this for your product?
Crush makes new ad images for your product from this ad: your logo, your product photo, your offer.
Trials from $19.95 USD, then $79.95 USD a month. Cancel anytime.
About this ad
- Meta Ad Library ID
- 1246523847081333
- Platforms
- Facebook, Instagram and Audience Network
- Relaunches
- 0
- Niche
- Insurance
Ad text
If your restaurant insurance premium just jumped 20%… 30%… even 40%… And nothing changed in your operation… You’re not wrong to question it. We hear it constantly: “Our workers comp went up 38% and nothing changed.” “They just doubled it and said ‘market conditions.’” “We’ve had zero claims and they still jacked it up.” Yes — rates can rise. But not every increase is simply “the market.” Because we're actually helping most restaurants save up to 25% off on their insurance, whilst getting them more coverage. In many cases, there are structural drivers behind those numbers. Payroll estimates. Class codes. Experience modification factors. Audit adjustments. Carrier appetite shifts. Coverage limits. End-of-term corrections. The issue isn’t that premiums move. It’s that most restaurant owners never see a clear breakdown of why. They receive a renewal. They see a higher number. And they’re told it’s unavoidable. If you operate an established restaurant with 10+ employees and meaningful payroll exposure, workers comp alone can significantly impact your total premium. And if that policy wasn’t structured correctly from the beginning, you often feel it at renewal. Here’s what typically happens. At the start of the policy year, payroll is estimated. Classifications are assigned. Exposure assumptions are made. The year runs. At audit, actual payroll is compared. Class codes are reviewed. Adjustments are applied. If those elements weren’t aligned correctly at inception, the renewal reflects it. Not because you did something wrong. But because no one walked through it with you clearly. And that’s where frustration builds. You’re managing staff. Food cost. Labor. Vendors. Compliance. Customer experience. You don’t have time to decode insurance mechanics. But you also don’t want insurance to feel like something happening to you. Especially when margins are tight. Especially when payroll is substantial. Especially when you’re responsible for protecting both employees and the business you’ve built. At DMD Insurance Services, we’ve spent over 40 years working with established businesses — including restaurant operators with real payroll exposure and real operational risk. Our focus isn’t selling “cheap insurance.” It’s providing structural clarity. Because like we said, we can help you save up to 25% off on your insurance, whilst getting you more coverage... So your business is saving money, but covered for everything you need. When a restaurant owner requests a Coverage & Cost Review, we don’t just generate a quick comparison quote. We look at: How your current policy is structured Payroll classifications Workers comp class codes Experience modification impact Audit exposure Coverage limits Exclusions Recent renewal changes Only after understanding those drivers do we evaluate whether alternative carrier options make sense. Because switching brokers without understanding structure doesn’t solve the underlying issue. And for the restaurants we work with, that review doesn’t stop once the policy is placed. We check in quarterly. We review the payroll figures originally provided to your carrier. We compare them to current numbers. We give you the opportunity to adjust throughout the policy period. Why? Because waiting until the end-of-year audit is where painful surprises happen. Quarterly adjustments help reduce the risk of large audit corrections. They keep your structure aligned. They give you visibility throughout the year — not just at renewal. That level of oversight prevents small misalignments from turning into major premium swings later. In many cases, when policies are structured correctly, restaurant owners discover they were overpaying — and are able to lower their premium while improving coverage. But that only happens when the foundation is right. If you’d like to understand whether your current structure truly makes sense — and see what better alignment could look like — here’s what happens next. If a stronger structure or more competitive option is available, we’ll prepare a clear quote so you can see exactly how it impacts your cost and coverage. In many cases, once policies are aligned properly, restaurant owners are able to lower their premium while improving coverage. If your current structure is already solid, we’ll confirm that too. Either way, you walk away with clarity — and real numbers to make the right decision for your restaurant. If you’re ready to see what that looks like for your operation — Click the button below, and fill out the short form to request your Coverage & Cost Review below 👉
Where the ad sends people
fb.me
Tired of Your Restaurants Premiums Going Up?
40 Years Experience & Restaurant Specialist
Learn more: fb.me(opens in a new tab)