
Stopped· since May 3, 2026
- 6
- days it ran
- 4
- relaunches
Ad copy
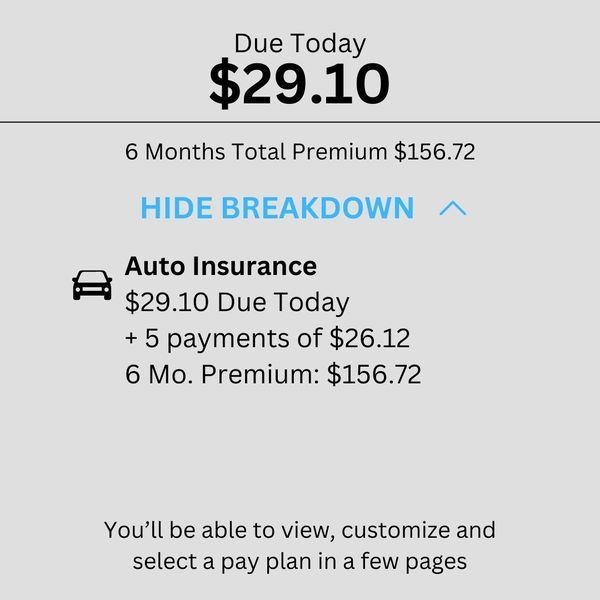
My son got his license in March and I was so proud. Sixteen years old, passed on the first try, didn't even clip a cone. I posted the picture. I cried a little. It was a whole thing. And then I called our insurance company to add him to the policy. And that's where the story gets interesting. Because I want to tell you what happened next, and I especially want to tell you how my sixteen-year-old ended up schooling me on personal finance in a way that I'm still a little embarrassed about. I was paying $174 a month for two cars. Fine. Not thrilling, but fine. I called to add Tyler to the policy figuring it would go up some. Everyone says it goes up when you add a teen. I was prepared for that. I was not prepared for what she actually said. "Okay, with the additional driver your new monthly premium will be $349." I said I'm sorry, can you repeat that. She said $349 a month. I said that's double. She said yes, adding a teenage male driver is one of the highest risk increases we have. I said he's never had an accident. He's never even had a ticket. He got his license eleven days ago. She said unfortunately the rate is based on statistical risk for the age and gender category, not individual history. I sat there after I hung up just staring at the phone. $175 more a month. That's $2,100 a year. For a kid who has never done a single thing wrong behind the wheel. I called my sister. She said yeah, that's just what it is. I called my friend Karen. She said the same thing happened to her when her daughter turned sixteen. Everyone just accepted it like it was weather. Like it was something that happens to you and there's nothing you can do. I didn't accept it. I spent the better part of a week calling other companies. Got four quotes. $362. $331. $378. $344. Every single one was in the same range or higher. One agent actually said "yeah teen drivers are tough, you're not going to find much better than what you have." I was livid. We're a one-income household. An extra $175 a month is real money. It felt like the whole system was designed so you had no choice but to just pay it. So here's the part I'm still a little humbled by. Tyler — my son, sixteen years old, the reason my insurance doubled — he's sitting at the kitchen table that Friday night and I'm venting. Going through the whole thing. The quotes, the phone calls, And he's just listening. And then he puts his phone down and goes "Mom, have you tried that site?" I said what site. He said "there's this tool a guy built that makes all the insurance companies compete against each other at the same time. My friend's mom used it." I said Tyler I spent a week calling every insurance company I could find. He said "yeah but this is different, you put your info in once and it just shows you the actual lowest rate." I said where did you even hear about this. He shrugged. He's sixteen. They know things. I looked it up. The story behind it is that some guy — young, local — watched his own parents getting crushed by their car insurance bill. They were paying over $300 a month, clean records, no accidents, no real explanation for why it was so high. So he built something. A site that takes your information and submits it to every major carrier simultaneously and just shows you the lowest rate each one will actually give you. Not an estimate. Not a range. The real number. He built it for his parents first. Then word spread. Tyler slid his phone across the table. "Just try it." So I did. Right there at the kitchen table. Took maybe 90 seconds. I put in both cars, put in Tyler as a driver, full coverage, everything. The quote came back $156 a month. I looked at Tyler. I said this has to be wrong. He said "that's what my friend's mom got too." I refreshed it. Still $156. The same coverage. Both cars. Teen driver included. I had been quoted $349 by four different companies and this thing came back with $156. I called my husband in from the other room. He looked at it and said "do it right now before it changes." We switched that night. That was five months ago. We've saved over $950 so far. And Tyler — I told him what we saved. He nodded like he already knew. Sixteen years old. I'm taking financial advice from a sixteen-year-old and it's working out. I told my sister. She has two cars and a seventeen-year-old. Was paying $412 a month. She switched. Now paying $161. She texted me "why did nobody tell us about this." I told my coworker Dawn. No teen driver, just hadn't checked her rate in a few years. Was paying $198 a month. She switched. Now paying $87. Said she felt like an idiot for not looking sooner. But the one that got me most was my neighbor Patty. She's been with the same insurance company for nineteen years. Two cars. Clean record. Paying $263 a month. She switched. Called me two days later. "Nineteen years. I've been overpaying for nineteen years." That one hurt to hear. Someone who did everything right, stayed loyal, and was still overpaying Here's what you actually get when you check. You get your real rate. Not a range, not an estimate — the actual monthly number for your specific cars, your specific drivers, your specific record. Most people find they can save up to $950 per year. You keep the exact same coverage. Same liability limits. Same protection. Takes about 90 seconds to see your number. You don't cancel anything first. You don't give a credit card. You don't have to shop around. You just see the rate. If it's not dramatically lower than what you're paying right now, you close the tab and nothing changes. But if you're like me, like my sister with her seventeen-year-old, like my neighbor who was loyal for nineteen years — it's going to be lower. A lot lower. Are you a safe driver who hasn't had a major accident or DUI in the past few years? Click Learn More to see your rate right now. Most people have no idea how much they're overpaying. But a guy who got tired of watching his parents get overcharged built something that will tell you. Now is the best time to act. Click Learn More to see your rate. If you're paying more than $150 a month and haven't checked your rate in the last six months, you're very likely leaving money on the table every single month.
Wow, I can't believe this actually worked!
LEARN MORELike this ad? Make it yours.
Crush rebuilds this exact creative around your product — your brand, your colors, your offer — in about a minute.