
Stopped· since Jun 3, 2026
- 12
- days it ran
- 0
- relaunches
Ad copy
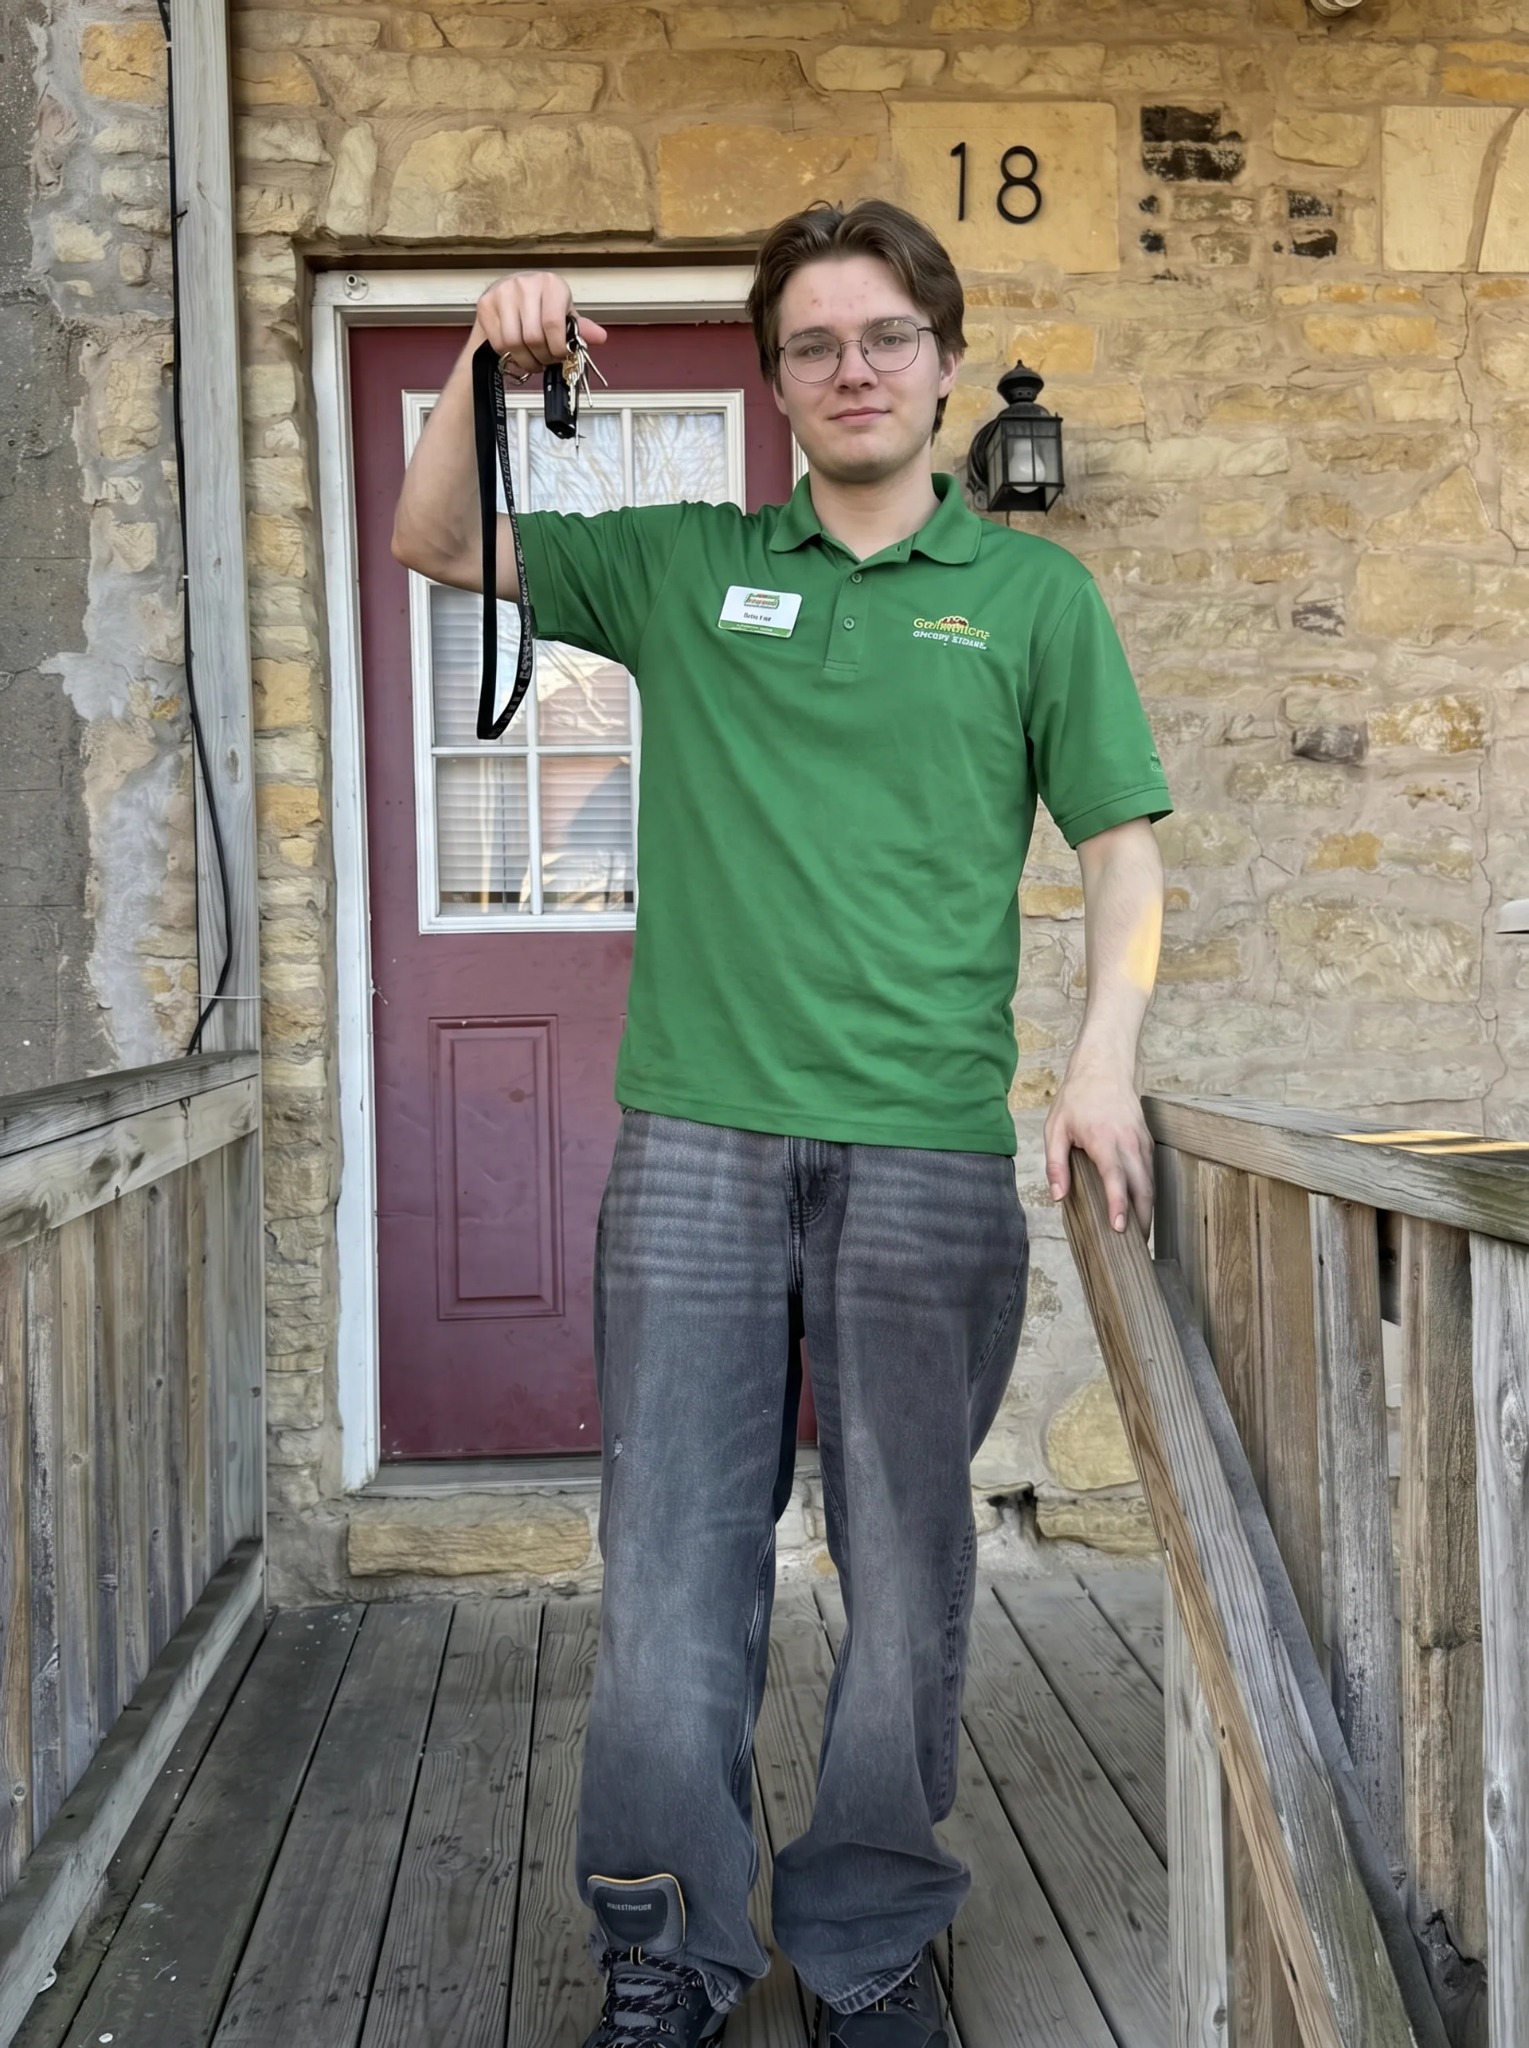
My son got his first real job and I almost ruined the moment by doing the math out loud. He came home wearing the polo shirt from the grocery store like it was a military uniform. Name tag already clipped on. Schedule folded in his pocket. He was going to work three nights a week after school and one Saturday shift, mostly bagging groceries and pushing carts, and he could not stop talking about it. I was proud of him. More proud than I probably showed. He had saved enough for a used Honda Civic from a guy my brother knew. Nothing fancy, 2013, a little faded on the roof, clean enough inside, ran well, and cheap enough that he could pay half and I could help with the rest. To him, it might as well have been a brand new truck. We drove over on a Sunday to look at it. He walked around it twice, checked the tires like he knew what he was doing, sat in the driver seat, and just smiled. I could see the whole future in his head. Work, school, practice, picking up his friends, not asking me for rides anymore. That part hit me harder than I expected. The next day I called to add him and the Civic to our insurance. We had been paying $238 a month for my truck and my wife’s SUV. I knew adding a teenage driver would raise it. I was not naive. I expected it to hurt a little. The new number was $589 a month. I asked the rep to repeat it because my brain rejected it the first time. She walked me through it calmly. Young driver, added vehicle, coverage selections, local rating factors, household driver profile. Nothing sounded strange. Nothing sounded like a mistake. It was just the number for that policy. I thanked her and hung up. Then I looked at my son’s work schedule on the kitchen counter. $14.25 an hour. Maybe 18 hours a week if school stayed manageable. After taxes, gas, and a little spending money, that insurance number made the job feel ridiculous before he had even worked his first shift. I did not tell him right away. That night he asked if I had called about the insurance. I said, “I’m still checking a few things.” He nodded, but I could tell he knew something was off. He had been excited all day, and now he was trying not to look too excited in case I gave him bad news. That is a miserable thing to watch as a parent. Two days later we had his final driving lesson. I was standing outside the driving school with another dad while the kids finished up. He had a son the same age, same situation, first job, first car, same nervous parent math. I mentioned the $589 number. He looked at me and said, “For one teen driver added?” I said yes. He told me not to make the decision off that first number. His family had been quoted over $500 too when they added their daughter. Then his wife checked CivilCarCoverage because another parent in their school group had posted about it. I asked what they ended up paying. He said their policy came back at $226 a month for two cars and their daughter’s older Corolla. Not bare minimum coverage, not some weird setup. Just a different option available for their profile. I was skeptical because teenage drivers are teenage drivers. I know why they cost more to insure. I was not expecting some magic answer. But I also did not want my son’s first job to turn into a lesson in how fast one monthly bill can swallow a paycheck. So I checked it that night. I put in my truck, my wife’s SUV, the Civic, our address, the drivers, and the coverage I wanted to compare against. I made sure the teen driver was included because I did not want a fake number that disappeared later. It took about two minutes. The number came back at $241 a month. For all three vehicles. I sat there quietly because I was trying to understand how $589 and $241 could both exist in the same week for the same family. The breakdown showed the quote was based on our vehicles, driving history, teen driver details, coverage level, and options available in our state. I called the number on the screen because I wanted a real person to walk through it before I said anything to my son. They confirmed the drivers, the cars, the coverage, and the monthly amount. Then I went upstairs. My son was at his desk pretending to do homework with the Civic listing still open on his laptop. I said, “We can do it.” He turned around fast. “The car?” “Yeah. The car.” He tried to play it cool for about three seconds, then gave up and started smiling like a kid again. We picked up the Civic that weekend. He drove it home with both hands on the wheel like he was transporting glass. I followed behind him in my truck the whole way, probably more nervous than he was. That was four months ago. He has not missed a shift. He pays his part every month without me asking. He learned very quickly that gas is not imaginary and that parking too close to shopping carts is a life choice. But the insurance number is the part I keep thinking about. I almost accepted $589 because I assumed that was just what happens when you add a teenage driver. I knew it would go up, so when it went way up, I treated it like something I was supposed to absorb. Checking took less time than the conversation I had been avoiding with my son. My brother used it for my niece a month later. Their first quote was $512 with her added. They found an option at $196. Another dad from the driving school checked before buying his son’s first truck. He said it saved him from telling the kid he had to wait another six months. If you are adding a teen driver, buying a first car, or trying to make a kid’s first job actually make sense, check the insurance number before you assume the first quote is the only path. This is where I checked ours: CivilCarCoverage. https://civilcarcoverage.com/form/?c=20207&source=rd2.tst.03jn.9
Adding a driver?
Complete the CivilCarCoverage form to compare free, no-obligation auto insurance quotes. Your privacy is protected—no spam, no hassle.
SEE DETAILSLike this ad? Make it yours.
Crush rebuilds this exact creative around your product — your brand, your colors, your offer — in about a minute.