
Stopped· since Nov 30, 2025
- 130
- days it ran
- 0
- relaunches
Ad copy
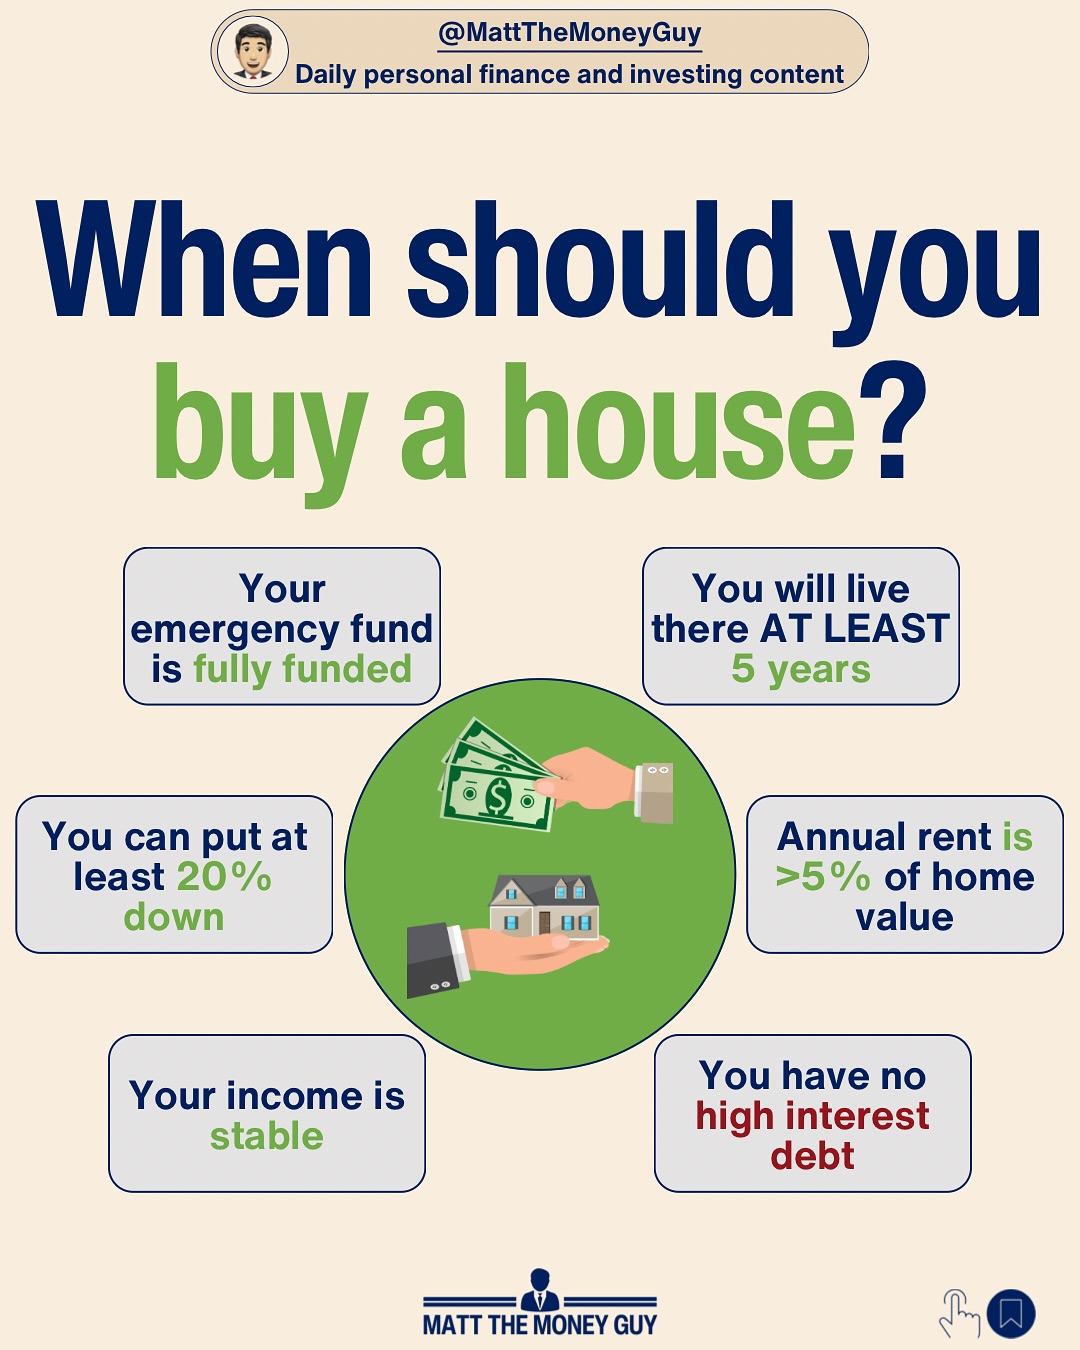
Follow me @mattthemoneyguy for DAILY personal finance content! This first post is sure to get some real estate agents fired up, but it’s just something I have to say. In general, people rush into buying homes before their ready and it hurts them. I know homes are expensive right now relative to incomes, but that doesn’t change the math of what you can afford. Putting 3.5% down, buying a home while you have other debt, or buying a home before you’re certain where you want to settle are all great ways to make yourself WORSE off than renting. A bit more detail: ➡️ Don’t buy a home if you don’t have enough cash to last you for a MINIMUM of 3-6 months unemployed with $0 income (i.e, an emergency fund). ➡️ You should plan on being there AT LEAST 5 years (ideally longer) if you buy. It simply does not make sense with closing costs to stay any shorter ➡️ 5% of your home’s value should be less than what your annual rent WOULD be. This is a rule of thumb and could vary depending on your situation, but gives a general sense of a good deal on a home. ➡️ Do not buy a house if you still have credit card debt. Being high interest debt free is step 1 of getting your finances in order, buying a house is way past that. Don’t skip steps. ➡️ This goes without saying, but if your income is unstable in any sense, I would not buy a home. ➡️ Finally (and possibly most controversial), I would not buy a home unless you can put a full 20% down. It’s simply too much leverage on an asset for an average consumer to put down any less. Am I missing anything? Drop it in the comments! - Matt
Like this ad? Make it yours.
Crush rebuilds this exact creative around your product — your brand, your colors, your offer — in about a minute.