Simple Choice Insure
 Facebook ad: “Homeowners need to read this”
Ran for 5 days, from April 10 to April 15, 2026, the last day Crush saw it.
Run by Simple Choice Insure on Facebook. Crush is not the advertiser and does not verify its claims. See this ad in Meta's Ad Library(opens in a new tab)
Want an ad like this for your product?
Crush makes new ad images for your product from this ad: your logo, your product photo, your offer.
Trials from $19.95 USD, then $79.95 USD a month. Cancel anytime.
About this ad
- Meta Ad Library ID
- 1453326536062531
- Platforms
- Relaunches
- 0
- Niche
- Insurance
Ad text
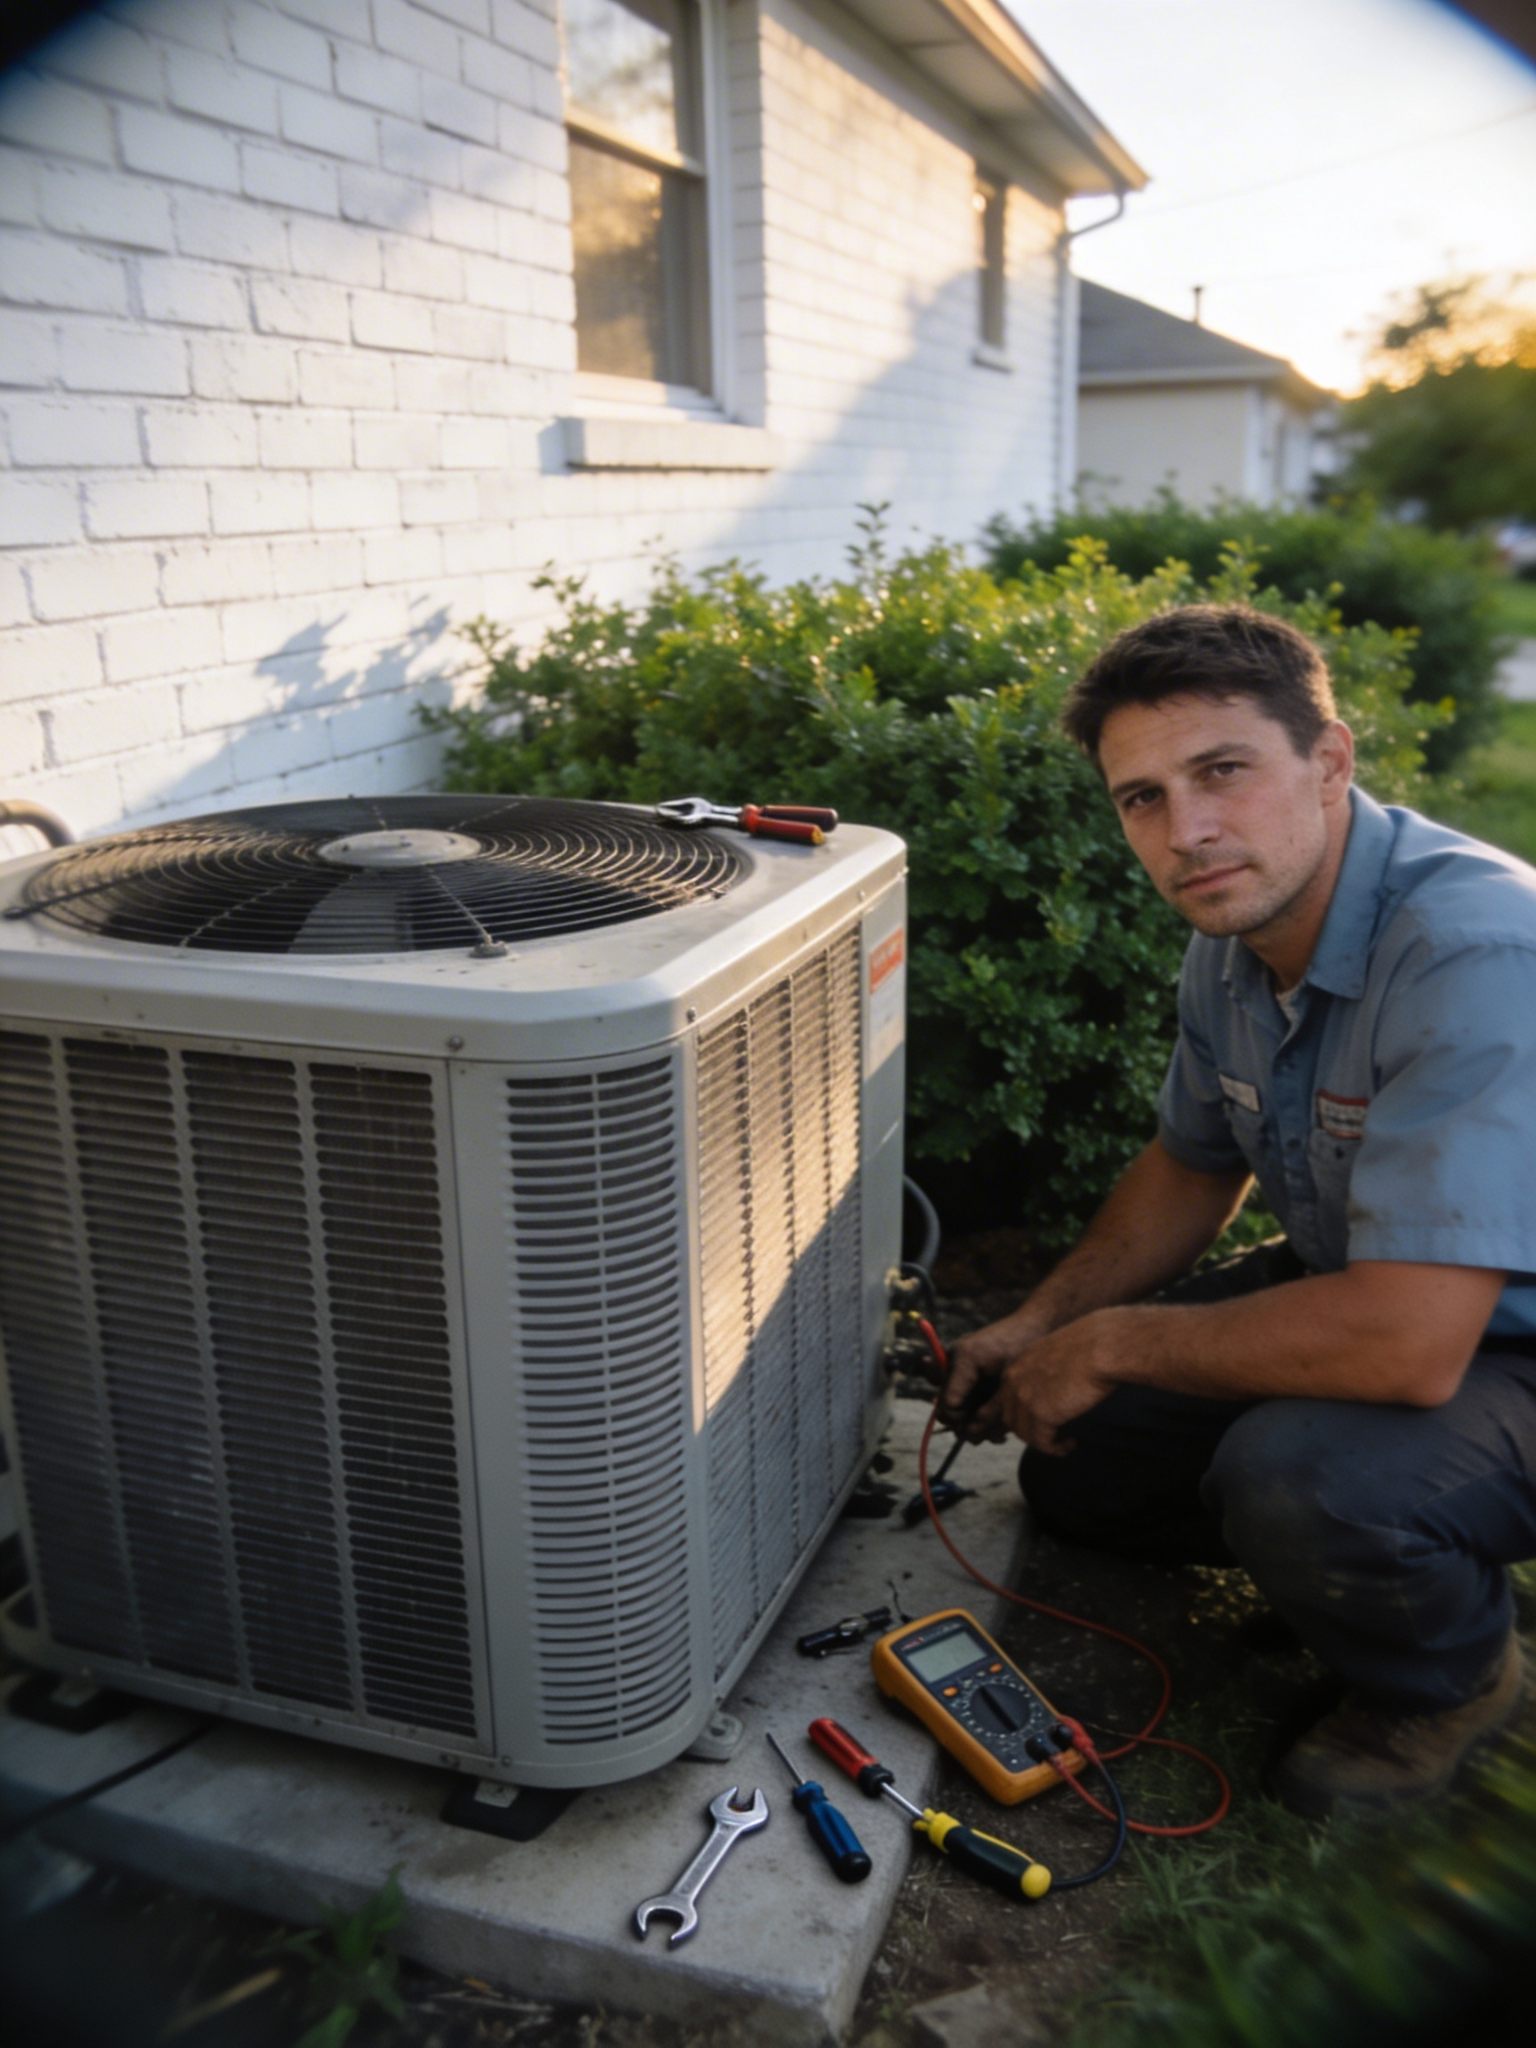
How I started protecting my family's home for $27 a month after getting quoted $95 and walking away for two years. The difference wasn't my health, my age, or my credit score — it was the way the coverage amount was being calculated from the start. I want to be clear about who I am before any of this makes sense. I run HVAC. Been doing it fifteen years. I leave the house at six in the morning and most nights I'm not back until after dinner. We bought our house six years ago. Three kids. A mortgage payment that doesn't move. Property taxes that do. I'm not the guy who has his finances figured out. I'm the guy who knows what needs to get done and works until it is. And for two years I had this one thing sitting in the back of my head that I couldn't solve. My family had no coverage. Zero. And every time I tried to fix it, I hit the same wall and walked away feeling like the problem wasn't built for someone in my position. That's the part nobody ever says out loud. It's not that guys like me don't try. It's that we try, we get the number, and we quietly decide it must not be meant for us. The first time I tried to fix it, a guy at an insurance agency sat me down and quoted me $95 a month. I had budgeted maybe $40 in my head before I walked in. He said that was the number for someone my age with a family, and I believed him. I thanked him for his time and drove home and didn't touch it again for eight months. The second time I actually got somewhere. I found a term life policy through work, $61 a month, and I held it for almost two years. Then property insurance jumped 22% the same month my truck needed a transmission. Something had to go. The policy was the thing that felt like it could wait. It always feels like it can wait. The third time I got a piece of mail with $5.50 a month printed in big numbers on the front. I read the back. Accidental death only. I threw it in the recycling bin on top of the pizza box and didn't think about it for a week. What I was left with after three tries was the same conclusion every time. The real stuff costs more than I can make work. The cheap stuff is designed to not pay out. Every dollar I bring in is already spoken for. I know I need this. I just can't find a number that fits the life I actually have. I stopped looking. That's the honest version of it. I told myself I'd figure it out later and later kept moving further away. Here is the thing I did not understand for two years. The $95 quote was not wrong. The $61 policy was not wrong either. Those numbers were accurate for exactly what I was being sold. The problem was what I was being sold. Every agent I talked to built my policy around a coverage number that had nothing to do with my actual mortgage balance. They sized it for $300,000 or $400,000 in coverage. That is how they were trained. My mortgage balance is $185,000. Those are not the same number. The gap between them is the entire reason I could never make the math work. I was not priced out of protection. I was priced out of a coverage amount three times larger than the problem I was actually trying to solve. Once I understood that, the second part hit differently. My house is not just a house right now. I locked in at 3.6%. Today's rate is over 6%. If my family lost this place, they could not buy it back. Not at today's prices. Not at today's rates. The equity I have built and the payment I locked in years ago are a financial position that does not come back once it is gone. Twenty-something dollars a month stopped feeling like a cost I could not afford. It started feeling like a lock on something irreplaceable. It was a Thursday night. I was on the couch, phone in my hand, not looking for anything. Just scrolling. A guy had written a post about this exact thing. I do not know him. He does trades work, different county. He had written out the same sequence I had just lived. The $90 quote that ended the conversation. The policy he held for a while and then dropped. The part where he stopped trying because the numbers never worked for someone in his position. And then he wrote a number. Twenty-seven dollars a month for a $185,000 balance. I read it twice. I did not click on anything that night. I read the post again the next morning before work and then I went through the process on my lunch break sitting in my truck in a parking lot. I expected the wall. That is the only way I know how to put it. I have hit it enough times that I was already braced for it. It did not come. What I found on the other side was a policy sized to my actual mortgage balance, not to a number some agent picked out of a training manual. The death benefit stays the same for the entire term. It does not shrink as the years go on. The payout goes to my family, not to the bank, and they can use it however they need to. The premium is locked. It will not go up. That was the part that mattered most to me. I had lapsed a policy before because a number I thought I could hold became a number I could not. This one is the same number it will always be. A few weeks after I started the policy, I ended up talking to a guy named Mike through a local trades group online. Landscaper. Same county. He had let two policies lapse over eight years, one whole life plan his agent pushed at $88 a month that he held for six months before it became impossible, one term policy that lasted longer but went the same way when a slow season hit. He found this about four months before I did. He is covering a $162,000 balance. He is paying $24 a month. He told me the thing that changed it for him was the same thing that changed it for me. He was not being priced out of coverage. He was being quoted for an amount that had nothing to do with the number on his mortgage statement. Once the sizing was right, the number was finally one he could hold. A few people from that trades group have asked, so I want to be upfront about where I found it. After I started the policy I went back and searched every platform I could think of. Every result was built around the same model I had always been quoted under. Large face amounts, premiums priced for a coverage tier that had nothing to do with the balance on my actual mortgage. That is how those platforms are organized. A policy sized to your real mortgage balance is not a category they carry yet. The only reason I had it was because that post crossed my feed on a Thursday night when I was not looking for anything. I am sharing this because I spent two years convincing myself the numbers just do not work for guys in my position. I let a policy lapse because I believed that. If someone reading this has landed in the same place, the company is Simple Choice Insure. The link is below. Drop LAPSED below if you've ever let a policy go because the number stopped making sense for the life you're actually living. If you have been here before, I am not going to tell you that this is different and expect that to land. You have tried. You got a number that did not work. You held something as long as you could and then you let it go. You told yourself you would come back to it and you did not. That is not a character flaw. That is what happens when you keep getting quoted for a problem three times larger than the one you actually have. The policy did not lapse because you made the wrong decision. It lapsed because the number was built wrong from the start. That is the only thing that changed here. Not the product. Not some new version of something you have already seen. The sizing. And when the sizing is right, the number is finally one that holds.
Where the ad sends people
simplechoiceinsure.com
Homeowners need to read this ☝️
Get a free mortgage protection insurance quote in 3 simple steps. Guaranteed acceptance, affordable coverage, and quick approval. Get yours now!
Get quote: simplechoiceinsure.com(opens in a new tab)