
Active· since May 29, 2026
- 109
- days running
- 0
- relaunches
Ad copy
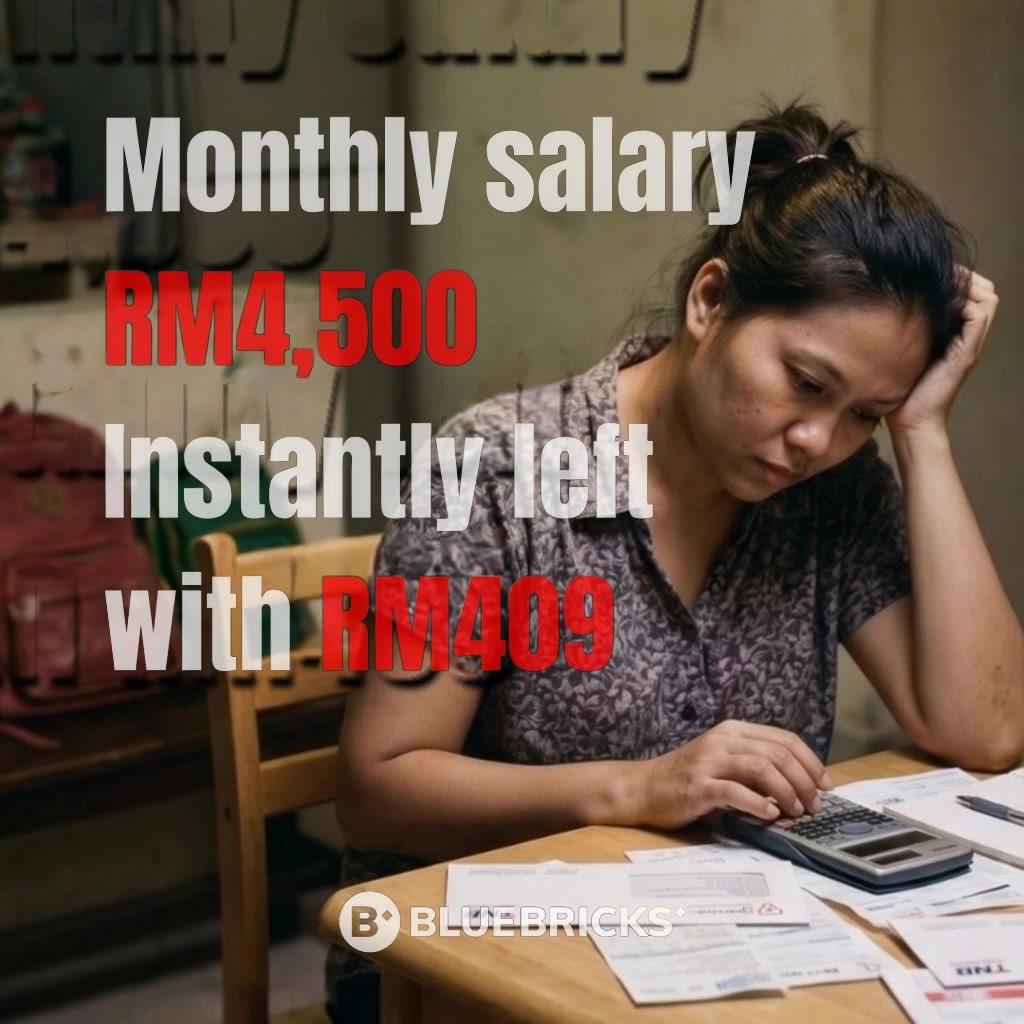
[RM4,500 Salary. RM406 Left.] —— Is this really what she chose? Saw a news article the other day. A 33-year-old female teacher. Civil servant. Been teaching for 7 years. Monthly salary RM4,500. Three kids. Husband is self-employed, income unstable. She said she's considering filing for voluntary bankruptcy. The comments section exploded. "RM4,500 still not enough? Spoiled." "You're a civil servant — stable job, what more do you want?" "Must be she doesn't know how to manage money." I read through the comments, flipped back to her income breakdown. Picked up the calculator, followed her numbers line by line. RM4,500. Minus EPF, SOCSO, mortgage, car loan, insurance, utilities — RM1,400 left. Minus AKPK monthly payment of RM770 — RM630 left. Minus Aeon credit RM224 — RM406 left. RM406. Whole family. Three kids. One month. I put the calculator down. Stared at the number. Had to pause. ▋ How would you stretch RM406 over a month? RM406 divided by 30 days. RM13.50 per day. Three meals for the family. Kids' school allowance. Tissues, detergent, gas. A kid gets sick and needs a doctor. School uniform tears and needs replacing. Husband's income is unstable — good months he chips in, bad months she carries it alone. RM13.50 a day. And she's not someone who did nothing. She already went to AKPK — the credit counseling and debt management agency. She already took the "ask for help" step. AKPK restructured part of her debt. The RM770/month payment is already what was negotiated. But even after reaching out, every month's deductions still leave RM406. The people in the comments saying "RM4,500 isn't enough?" — they saw the first number. They didn't follow through with the subtraction. They don't know that RM4,500, after all those mandatory deductions, isn't RM4,500 anymore. ▋ Nobody becomes this in a day Nobody wakes up one morning and finds themselves with RM406 left. It's one payment at a time, one month at a time, getting there. I've met a lot of people who ended up somewhere similar. There's one thing in common — before things truly collapse, everyone had a stretch of "something doesn't feel right." The few days before payday, starting to count what's left in hand. After the math, telling yourself: just hold on, next month will be better. Next month comes. Same. The month after that. Same. That "doesn't feel right" feeling — it didn't turn into action. It's not because they weren't smart. It's because stopping to face that number is harder than continuing to push through. And there's another voice inside: "I earn this much, how did I end up like this? Is it my fault?" That voice sounds exactly like the comments section. The difference — people in the comments say their piece and move on. You carry that voice home, every day, into a number that keeps shrinking. ▋ She's calculating what she can keep In her post she asked a few questions: "If I go bankrupt, will the civil servant housing board auction my house? I only have one car, will the bank take it?" You can see it — she's calculating. Calculating what she'd still be allowed to keep if she actually took this step. And she's a civil servant. For civil servants, bankruptcy consequences are heavier than for most — possibly losing promotion eligibility, work qualification issues too. She knows. And she's still considering it. Which means the days of continuing to push through might be worse than what comes after bankruptcy. I don't think her considering it is wrong. She held on for a long time. Every deduction is necessary. At some point, a person needs an exit. I just keep thinking — if earlier, back when it was still "something doesn't feel right," somebody had helped her lay out her entire debt structure on the table — would things have been different. Not definitely. But possibly. ▋ Have you actually done the math on your own numbers? She made her numbers public and got attacked for it. Most people can't even make themselves calculate their own. You know your salary. You roughly know your mortgage and car loan. But have you actually sat down, like she did, subtracted every line item, looked at what's left? A lot of people don't do it. The reason is fear. Fear of what the number tells them — a fact they don't want to hear. ▋ Earning more doesn't mean having more left Been in this work long enough, I learned one thing. Clients on RM3,000 a month and clients on RM8,000 a month — the number left after deductions, a lot of the time, isn't that different. Income goes up, the car gets bigger, the house gets nicer, lifestyle rises, credit card limits rise too. What you can spend grows. What you can owe grows with it. Income level isn't the point. The point is what's left after the deductions. ▋ Before that number gets smaller That "something doesn't feel right" feeling — those few days before payday when you start counting money — that's the signal. You don't have to wait until RM406 to call it a problem. When you start being afraid to calculate, afraid to look, afraid to face — the problem is already there. Try doing what she did. Subtract your salary line by line. Look at the final number for a full minute. If that number makes you uncomfortable, you can have someone take a look at whether your debt structure can be arranged differently. No commitment required. Some people's debt can be restructured, and the monthly payment comes down. Restructuring is bringing your payments back to a rhythm you can actually keep. At minimum, give that number enough room to breathe. RM4,500 isn't small. But enough or not — look at what's left after the deductions. Getting a bank loan isn't as hard as you think — BlueBricks https://www.bluebricks.com.my/fb-en-personal-loan-with-high-commitment-problems/
RM4,500 Salary. RM406 Left.
WHATSAPP MESSAGELike this ad? Make it yours.
Crush rebuilds this exact creative around your product — your brand, your colors, your offer — in about a minute.